
Does insurance cover my roof? Answer 5 quick questions and see how likely your damage is to be covered. This checker is based on how standard New Jersey homeowners policies treat roof damage and on the claims we help homeowners with every month.
Check my coverageThis is an estimate, not a coverage decision. Only your insurance company can decide what your policy pays.
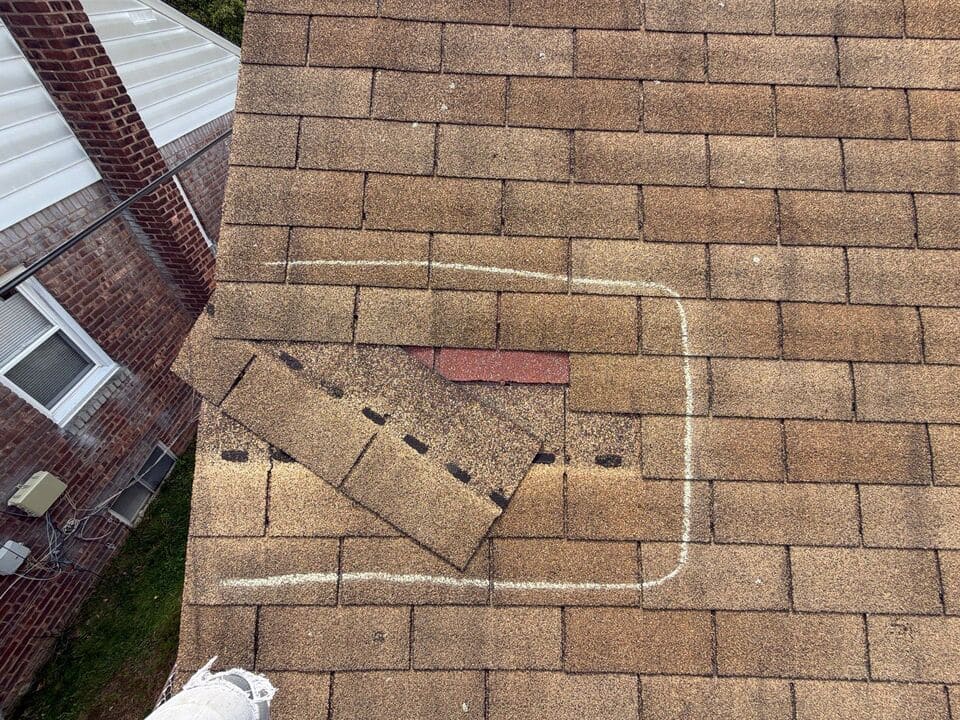
📞 Call (844) 423-1235 Book a free damage inspectionSo, does insurance cover my roof? In most cases it does when the damage was sudden. A standard New Jersey homeowners policy (usually an HO-3) covers sudden and accidental damage. For roofs, that normally means:
Learn more in how a roof insurance claim works in New Jersey, RCV vs ACV: what really pays for your roof and our insurance claim assistance service.
If you believe your insurer is handling your claim unfairly, you can contact the New Jersey Department of Banking and Insurance (DOBI) consumer line at 1-800-446-7467.
It depends on the cause. A leak caused by storm, wind or hail damage is usually covered. A leak caused by old, worn-out shingles or poor maintenance usually is not.
It can, depending on your insurer and your claim history. That is why we recommend an inspection first, so you only file when there is real, documented storm damage.
Yes, when the storm damage is widespread enough that a repair would not restore the roof. The adjuster decides based on the damage and your policy.
Often yes. Adjusters sometimes miss damage. A detailed inspection report with photos can support a request for re-inspection. We review denied claims for free.
Written and reviewed by the Jay Global Home roofing team
Jay Global Home LLC is a New Jersey licensed home improvement contractor (HIC #13VH13555200), insured and GAF Certified, based in West Orange. We document storm damage and work with homeowners and adjusters on roof claims across Essex, Morris, Sussex and Union County.
This tool gives general information, not legal or insurance advice. Your policy wording decides your coverage.